


Articles
- BLOG / Articles / View
- Articles
Halliburton’s Perspective in Q3 2026: Key Takeaways
By Avik on November 2, 2026 in Articles
Industry Outlook
Halliburton (HAL) sees its international businesses at their strongest level in years. These operations are growing, profitable, and winning work through technology and execution. Its management expects these regions to grow about 12% year over year in 2026.
For 2027, management expects mid-single-digit revenue growth and operating margins near 15%. That would mean about 200 basis points of expansion. The outlook assumes flat North American activity, Middle East activity near second-half 2026 levels, and continued growth elsewhere. Better core margins, new work, and cost reductions should help. The ramp-down of S/4-related costs is another driver.
Frac Market Analysis
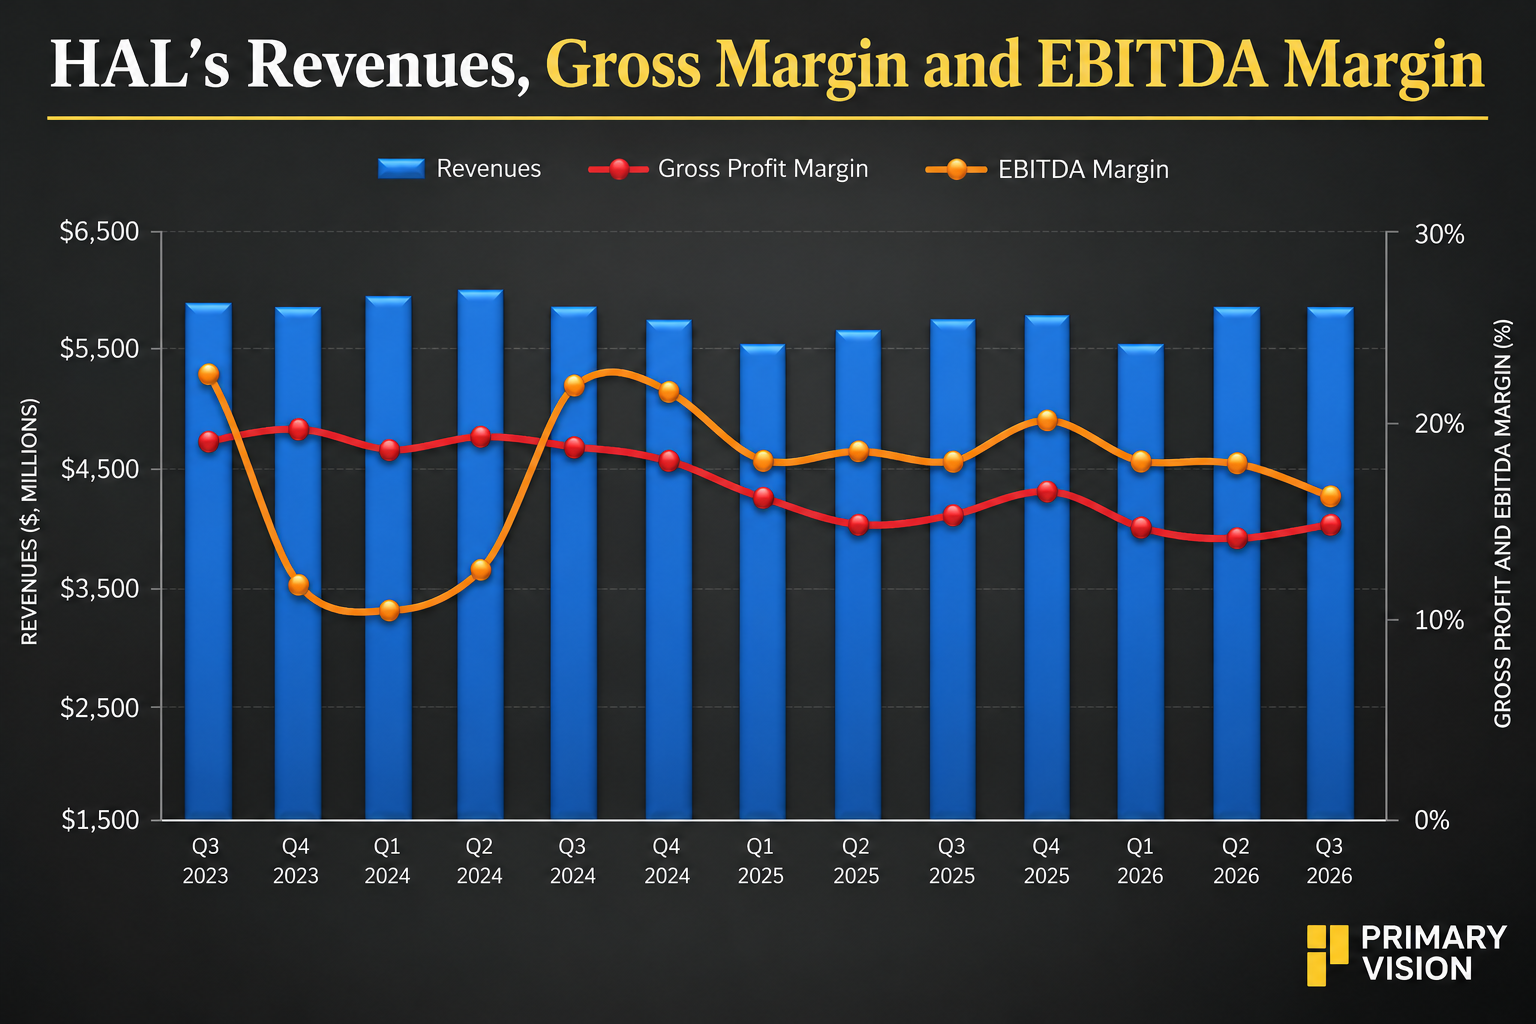
North American frac was weaker than expected. Q3 revenue fell 5% sequentially to $2.2 billion. Moving crews to new customers at better pricing caused more downtime than planned, weighing on regional and Completion & Production results.
Halliburton prioritizes returns over market share and says its 2027 growth plan does not require a North American frac recovery. Any recovery would be upside, as the outlook rests on stronger performance elsewhere.
International frac offers clearer growth opportunities. Q4 should benefit from a full quarter of Jafurah completions and greater service share in Saudi Arabia. Halliburton also expects its first ZEUS electric frac fleet in Argentina to start up and its North Sea stimulation vessel to begin operations around year-end. These projects support the growth outlook, but timely execution and revenue conversion remain key.
Other International Growth Drivers
Halliburton is expanding beyond fracturing. In Argentina, it won a multiyear artificial-lift rental contract and completed its first unconventional installation. It also made its first artificial-lift installations in the UAE and offshore Congo, and received its first offshore ESP order in Brazil.
Venezuela is another potential growth market. Halliburton reopened facilities, moved key equipment and generated Q3 revenue across several product lines. Management expects growth to continue as customer activity improves.
The strategy is straightforward. Halliburton aims to win when customers value technology, execution and total cost of ownership. The pipeline is encouraging, but awards must translate into activity and profitable work.
Segment Forecast
For Q4, Completion & Production revenue is expected to rise 3–5%. Operating margins should improve 75–125 basis points. Management expects stronger performance in Latin America and the Middle East, seasonal completion-tool sales and steady North American land frac activity.
Drilling & Evaluation revenue is expected to fall 3–5% after a strong Q3. Margins should be flat to up 50 basis points. Product-line improvements and a better mix are expected to support profitability.
For 2027, management’s early outlook remains mid-single-digit revenue growth and about 200 basis points of operating-margin expansion to roughly 15%. This is a target, not a guarantee. New-work ramp-ups and cost reductions must deliver.
Relative Valuation
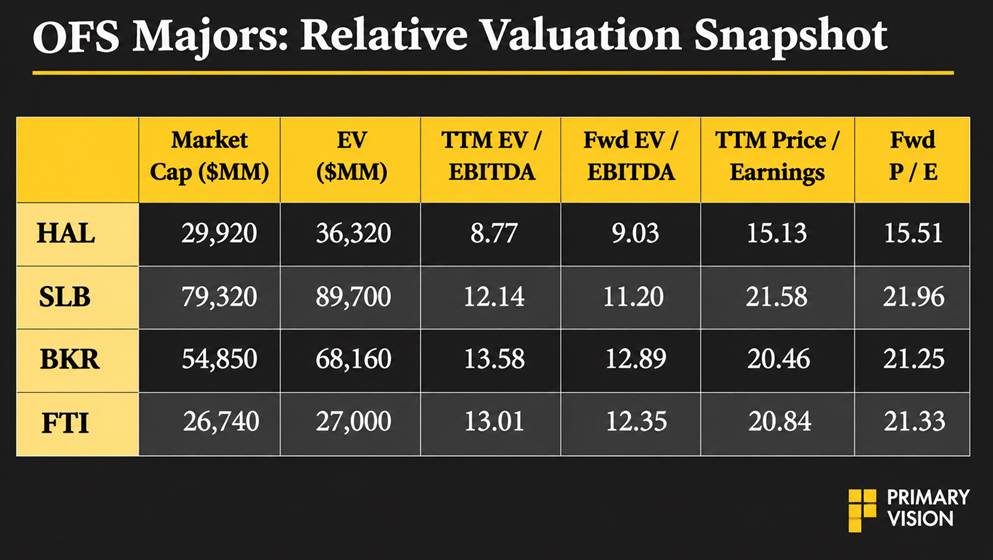
The latest working comparison puts HAL at about 8.8x trailing EV/EBITDA and 9x forward EV/EBITDA. Its trailing multiple is below SLB, Baker Hughes, and TechnipFMC. SLB and TechnipFMC show the opposite pattern.
HAL's forward EV/EBITDA multiple expansion versus the adjusted current EV/EBITDA contrasts with a decline in the multiple for its peers because the company's EBITDA is expected to decline versus a rise in EBITDA for its peers in the next four quarters. This typically results in a much lower EV/EBITDA multiple than peers. The stock's EV/EBITDA multiple is lower than its peers' (SLB, BKR, and FTI) average of 12.9x. So, the stock is reasonably valued compared to its peers.
Final Commentary
Halliburton’s Q3 update makes its growth story more clearly international-led. North American frac missed expectations, but management treats a recovery as upside. Jafurah, Argentina, the North Sea, and artificial lift provide growth opportunities. The key test is whether new work and cost reductions can lift margins while North American activity stays flat. The stock is reasonably valued compared to its peers.
Tags:
Permission denied
Upgrade to Pro Today and get…
• This article — plus dozens more each month, all within our full Research Module
• Frac Hits — our National-Level Frac Spread Count and Frac Job Count, updated weekly
• Frac Operator Monitor — detailed FSC & FJC by operator
• And so much more, designed to help you track, forecast, and outperform