The Market Explained
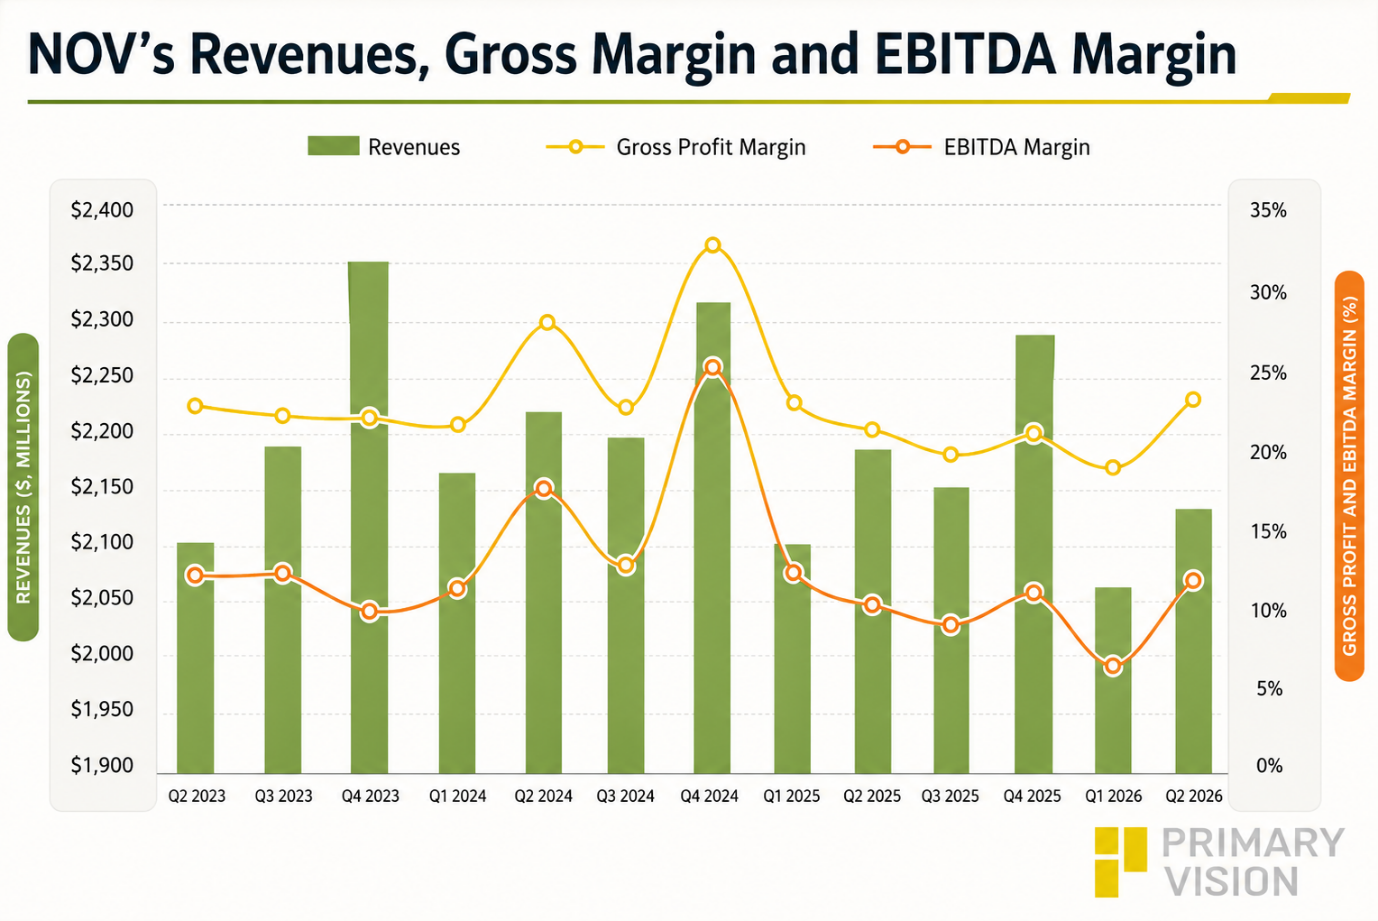
In our recent article, we have already discussed NOV's (NOV) Q2 2026 financial performance. Here is an outline of its outlook. NOV’s management estimates that uncertainty in the Middle East continues to limit visibility into activity. Operators are ready to resume work once takeaway capacity improves. Outside the region, market activity is gaining momentum. North American activity is improving, led by private operators. NOV is gaining share as customers prioritize efficiency, reliability, and lower well costs.
Geographic Drivers & Challenges
According to NOV’s management, Geopolitical uncertainty and commodity volatility are keeping some customers cautious. Energy Equipment orders remained below 100% book-to-bill, but management expects improvement later this year and stronger growth in 2027.
Middle East activity remains below pre-conflict levels, with higher logistics costs and some order delays. Unconventional activity remains strong despite supply-chain constraints. NOV’s global supply chain and flexibility helped it win work competitors could not execute.
Argentina demand is broad-based across drilling, completion, pressure pumping and coiled tubing. NOV is also supplying infrastructure and LNG equipment, including pumps, chokes, composite pipe and FLNG systems.
Strategy & Offshore outlook
NOV expects tight global service capacity, bringing capital equipment demand forward. Years of underinvestment and equipment attrition have reduced excess capacity, supporting earlier customer spending. NOV sees greater earnings potential, although geopolitical and commodity risks could still delay the recovery.
Offshore deepwater activity remains increasingly constructive, supported by energy-security concerns and declining North American production. According to NOV, ten FPSO awards are expected in 2026, up from six in 2025. The project mix is shifting toward gas-rich reservoirs and deeper, more complex developments, favoring NOV’s technology portfolio. As a result, offshore contracting activity rose 32% sequentially, with project starts expected to increase in late 2026 and early 2027. Higher rig utilization is also supporting aftermarket demand for spare parts, recertification, automation and equipment upgrades.
Q3 Forecast
NOV expects strong 2H 2026 growth from higher downhole tool sales, improved shipping and technology-driven market-share gains. Q3 Energy Products and Services revenue is expected to grow 5%–7% year over year, with EBITDA of $130–$150 million, slightly below the Q2 number.
Relative Valuation
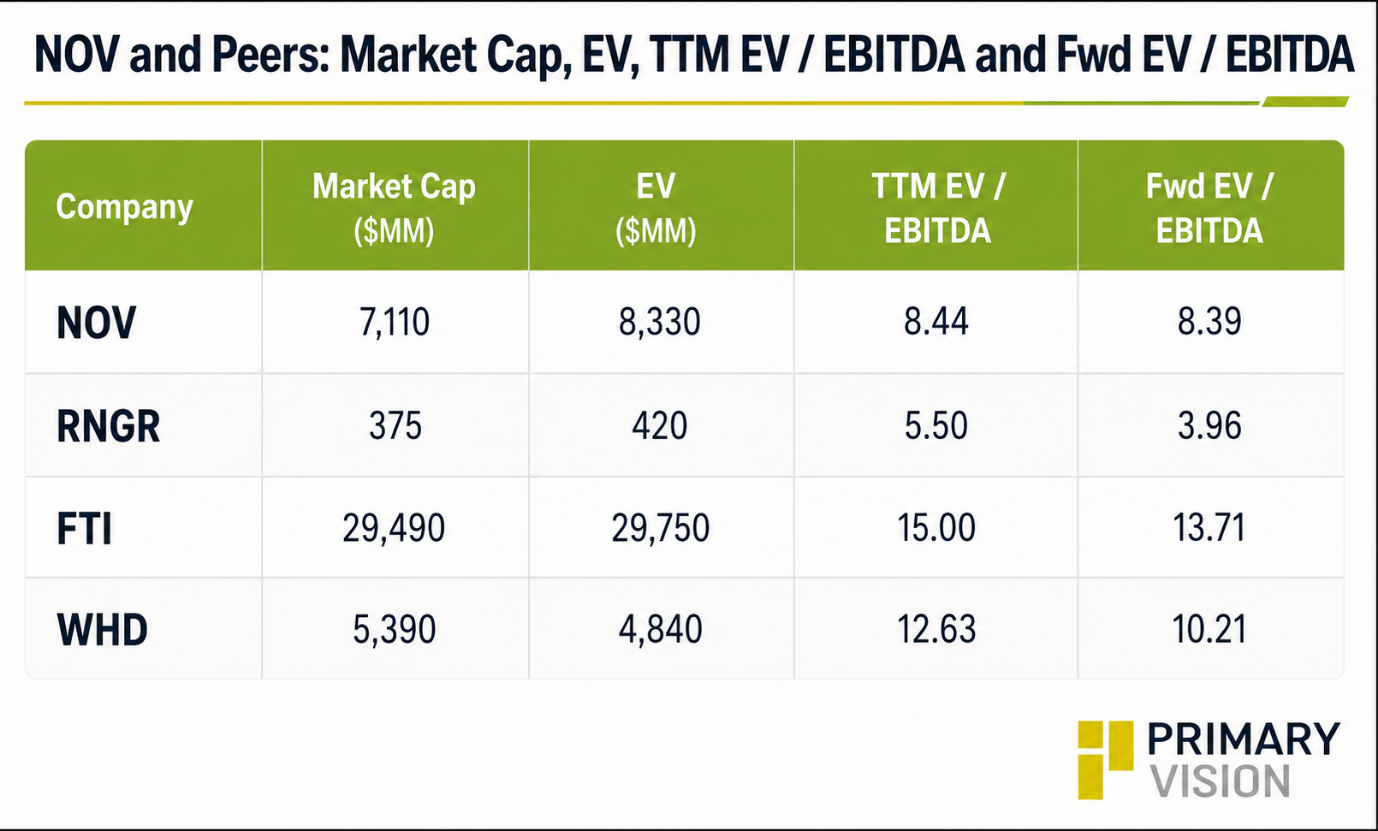
NOV is currently trading at an EV/EBITDA multiple of 8.4x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is nearly unchanged. The current multiple is lower than its five-year average EV/EBITDA multiple of 12.3x.
NOV's forward EV/EBITDA multiple versus the current EV/EBITDA contrasts with its peers because its EBITDA is expected to remain unchanged compared to a rise in EBITDA for its peers in the next year. This typically results in a much lower EV/EBITDA multiple than its peers. The stock's EV/EBITDA multiple is lower than its peers' (RNGR, FTI, and WHD) average of 11.0x. So, the stock is reasonably valued, with a negative bias, compared to its peers.
Final Commentary
NOV sees improving market conditions outside the Middle East, with North American activity gaining momentum. Tight global service capacity could bring capital-equipment spending forward in this cycle. Offshore markets are strengthening, with 10 FPSO awards expected in 2026 and contracting activity up 32% sequentially.
Argentina is also emerging as a broad-based growth market across drilling, completion, pressure pumping and LNG infrastructure. NOV expects strong second-half growth from higher tool sales, improved shipping and market-share gains. The stock is reasonably valued, with a negative bias, compared to its peers.