


Articles
- BLOG / Articles / View
- Articles
Patterson-UTI's Perspective in Q2 2026: KEY Takeaways
By Avik on September 4, 2026 in Articles
Patterson-UTI (PTEN) expects technology leadership and premium equipment to drive long-term growth and higher returns. Management believes tightening market conditions will continue to support stronger pricing across drilling and completions. The company is investing in higher-specification assets to expand earnings and free cash flow through 2027. Overall, Patterson-UTI remains well positioned for the next phase of U.S. shale development.
The Market Outlook
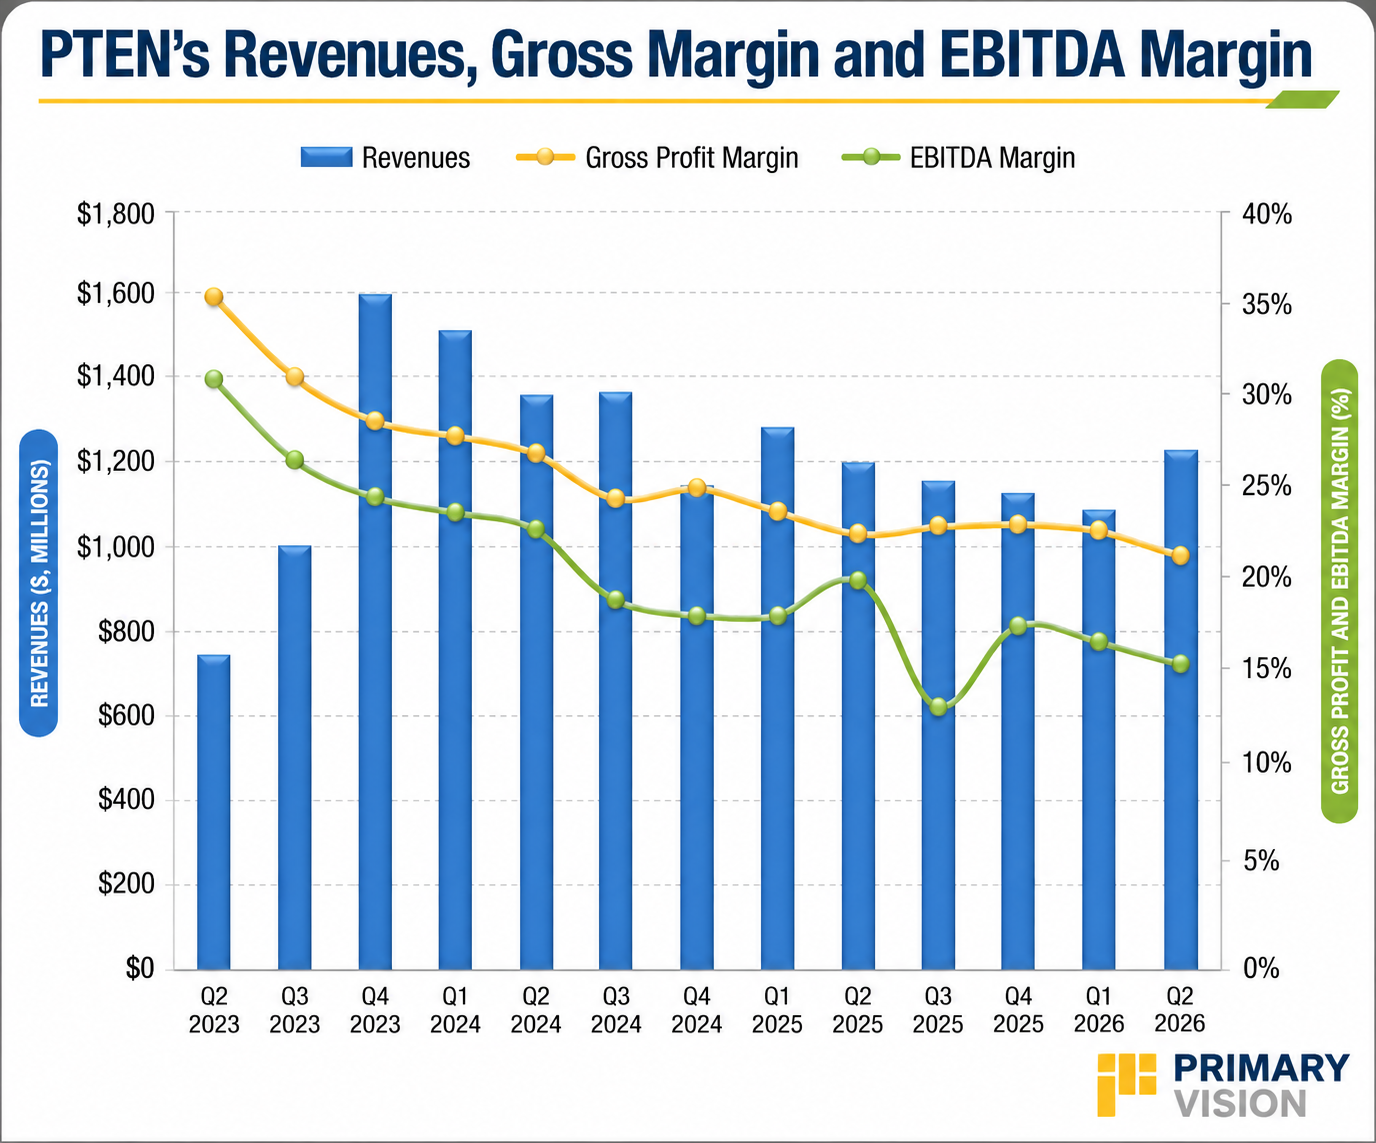
We discussed our initial thoughts about Patterson-UTI Energy's (PTEN) Q2 2026 performance in our short article a few days ago. This article will dive deeper into the industry and its current outlook. According to PTEN’s management, technology, execution, and operational performance are becoming the key differentiators in the oilfield services industry. The company expects these advantages to support premium pricing and higher returns across drilling and completions.
Management also expects its recent growth investments to drive higher profitability through 2027 and beyond. Overall, the company believes its technology leadership will strengthen its long-term competitive position.
Industry and Market Outlook
PTEN’s management believes customer demand is shifting toward higher-specification rigs, natural gas-powered completion equipment, and advanced automation. The company expects limited supply of premium equipment to support stronger pricing and returns. Higher oil prices continue to support a constructive outlook for U.S. shale activity through 2027.
Private operators are leading the current recovery, while public E&Ps are gradually increasing activity. Patterson-UTI expects future demand to be concentrated on its highest-specification drilling and completion equipment. Management believes this trend will support long-term growth and profitability.
Drilling Pricing Outlook
Management achieved 10–15% higher pricing on new contracts, with upgraded rigs commanding premium day rates. High-specification rigs remain in tight supply, supporting continued pricing strength across most U.S. basins.
Completion and Frac Outlook
PTEN’s completion activity improved sequentially in Q2 as pricing strengthened and frac calendars remained largely full. Management said customers continued working through a modest DUC inventory, supporting higher completion demand. The company believes natural gas-powered frac fleets are effectively fully utilized, while older diesel equipment remains less competitive.
Patterson-UTI expects the additional industry drilling activity to drive incremental frac demand in the second half and into 2027. The company's strategy remains focused on upgrading its fleet rather than adding total horsepower. By year-end, management expects about 90% of its active horsepower to be substantially powered by natural gas. This shift is expected to support stronger pricing, margins, and fleet utilization.
Cash Flow Outlook
PTEN expects current investments to drive higher earnings and cash flow beginning in late 2026 and into 2027. The company believes 2026 free cash flow will fully cover dividend payments while supporting its capital allocation strategy. Patterson-UTI expects these investments to deliver meaningfully higher free cash flow in 2027.
Relative Valuation
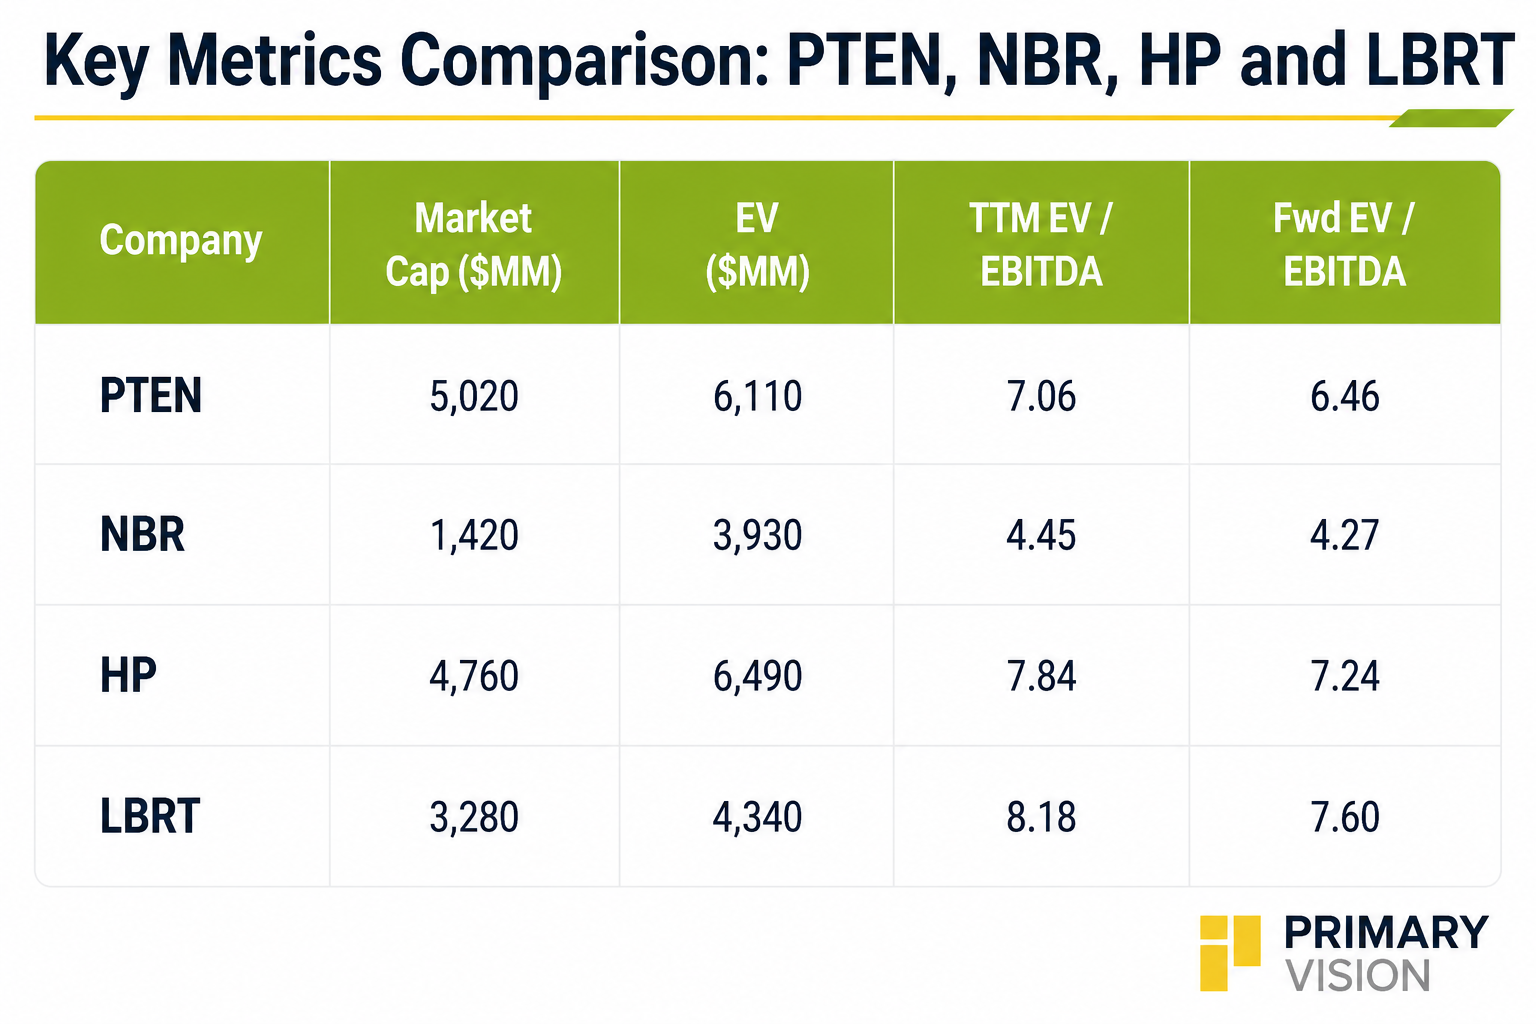
PTEN is currently trading at an EV/EBITDA multiple of 7.1x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is 6.5x. The current multiple is lower than its past five-year average EV/EBITDA multiple of 7.5x.
PTEN's forward EV/EBITDA multiple contraction versus the current EV/EBITDA is marginally steeper than its remain steady in the next year. This typically results in a slightly higher EV/EBITDA multiple. The stock's EV/EBITDA multiple is higher than its peers' (NBR, HP, and LBRT) average of 6.8x. So, the stock is reasonably valued compared to its peers.
Final Commentary
Patterson-UTI expects technology leadership and premium equipment to drive stronger pricing and long-term growth. Management believes demand for high-specification rigs and natural gas-powered frac fleets will continue to strengthen through 2027. Tight equipment availability is supporting higher drilling and completion pricing across the industry.
The company continues to upgrade its frac spreads, with approximately 90% of active horsepower expected to be substantially powered by natural gas by year-end. Management also expects recent growth investments to drive higher earnings and free cash flow beginning in late 2026 and into 2027. Overall, Patterson-UTI believes disciplined capital allocation and technology differentiation position the company for higher long-term returns. The stock is reasonably valued compared to its peers.
Tags:
Permission denied
Upgrade to Pro Today and get…
• This article — plus dozens more each month, all within our full Research Module
• Frac Hits — our National-Level Frac Spread Count and Frac Job Count, updated weekly
• Frac Operator Monitor — detailed FSC & FJC by operator
• And so much more, designed to help you track, forecast, and outperform