


Articles
- BLOG / Articles / View
- Articles
Pressure Pumping Ranking in Q2 2026: Tightening Capacity
By Avik on September 2, 2026 in Articles
Ranking Pressure Pumpers in Q2
This analysis evaluates Halliburton, Liberty Energy, ProFrac (ACDC), Patterson-UTI, ProPetro, and RPC using the same framework applied in prior quarters. The ranking combines execution and exposure signals, maintaining the established methodology so that quarter-over-quarter score changes remain comparable.
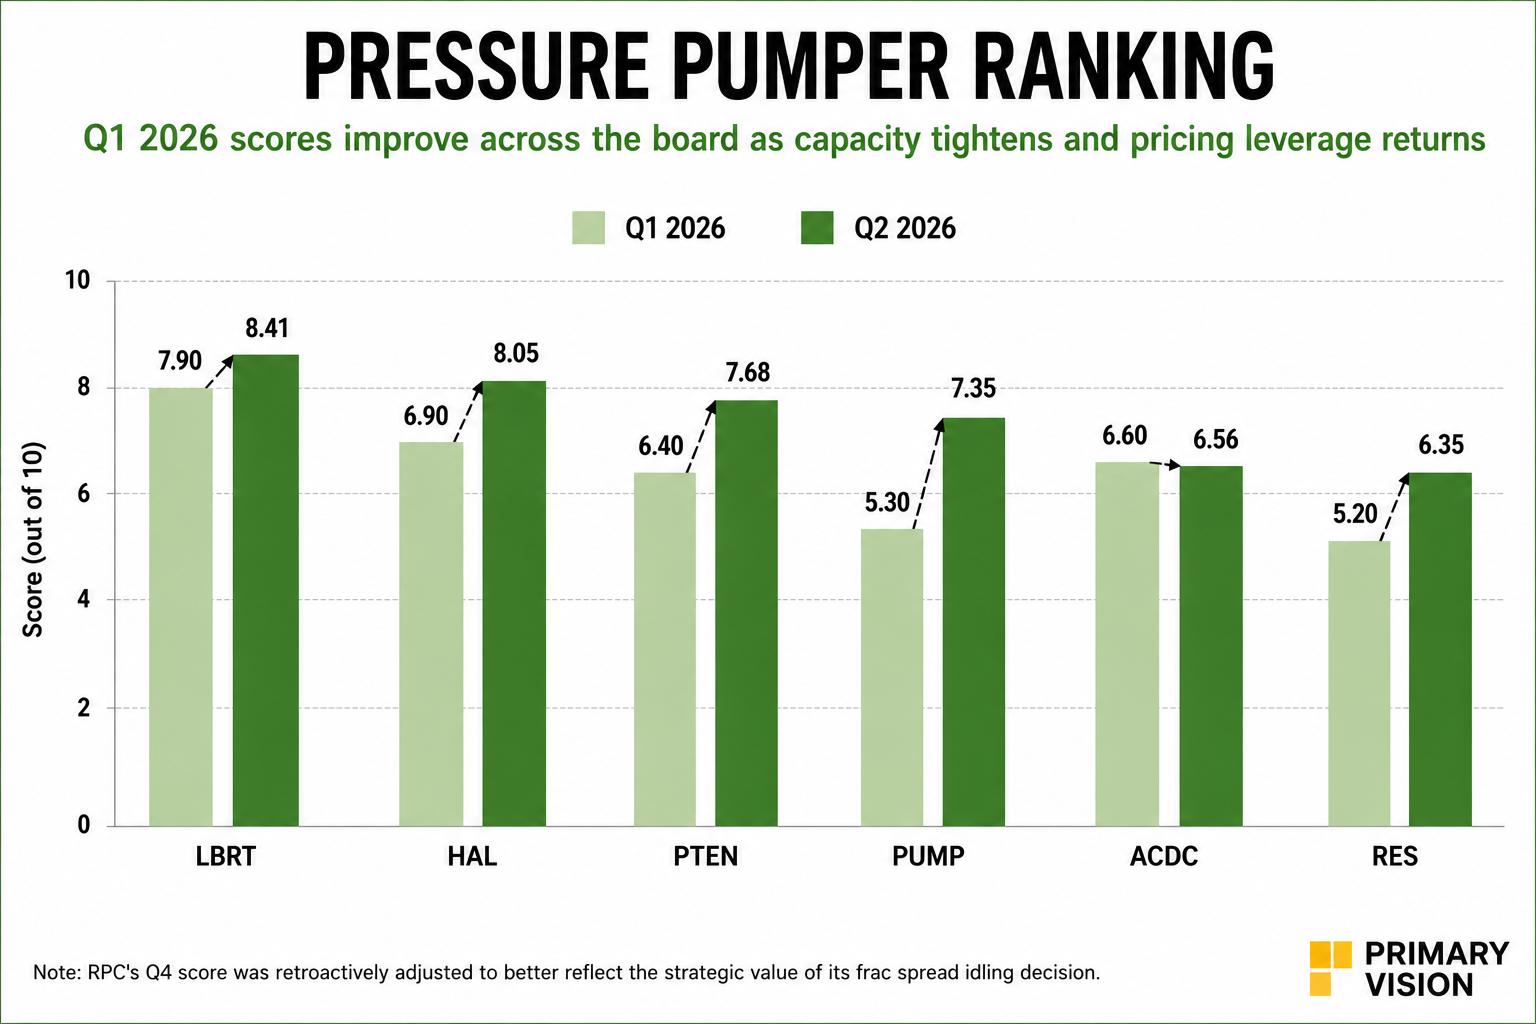
The Q2 ranking is led by Liberty Energy at 8.41, followed by Halliburton at 8.05. Patterson-UTI moves into third at 7.68, followed by ProPetro at 7.35. ACDC ranks fifth at 6.56, while RPC remains sixth at 6.35.
Liberty Energy: Leadership Holds
Liberty remains the highest-ranked pressure pumper, with its score increasing from 7.90 to 8.41.
The company's leading position reflects the combination of high fleet utilization, pricing discipline and a differentiated technology portfolio. Its Q2 results also reinforce the value of having additional growth avenues through power and technology.
Liberty therefore continues to set the benchmark for the group, although the more important changes this quarter are occurring further down the ranking.
Halliburton: Stronger Position
Halliburton increases from 6.90 to 8.05, strengthening its position as the group's second-ranked company. Scale, technology and geographic diversification remain important advantages. Improving North American conditions provide additional support, while international operations continue to broaden the company's exposure. The Q2 improvement creates greater separation between Halliburton and the companies below it.
PTEN: Moves Into Third
Patterson-UTI records one of the largest improvements in the ranking, increasing from 6.40 to 7.68 and moving from fourth to third. The company's completion business is benefiting directly from tighter available capacity. Near-full utilization and improving pricing are translating a stronger operating environment into better financial performance.
PTEN's move ahead of ACDC is one of the clearest examples of how changing fleet economics are affecting the relative ranking.
ProPetro: Largest Score Improvement
ProPetro increases from 5.30 to 7.35, moving from fifth to fourth. The improvement reflects better conditions in pressure pumping as well as growing commercial relevance for PROPWR. The power-generation platform provides an additional avenue for growth and broadens the company's positioning beyond traditional completion services. The combination produces the largest score improvement in the group.
ProFrac: A Relative Decline
ProFrac (ACDC) score changes only modestly, from 6.60 to 6.56, resulting in a move from third to fifth. The company continues to show operating improvement, including better stimulation activity and pricing. However, its relative position has weakened as PTEN and ProPetro have improved more rapidly.
The result highlights an important feature of the current market: absolute improvement is not necessarily sufficient to maintain relative ranking as available capacity tightens.
RPC: Improvement Continues
RPC increases from 5.20 to 6.35, continuing its improvement from the previous quarter. Better pricing and activity conditions provide a more constructive operating backdrop. However, the company's smaller scale continues to limit its overall positioning relative to the larger pressure pumpers.
RPC remains sixth, although its score has moved substantially higher over the past two quarters.
Capacity, Pricing and Fleet Positioning Drive the Re-Ranking
The Q2 ranking is increasingly being shaped by what happens inside the utilization numbers. Tightening available capacity gives operators greater opportunity to improve pricing, keep fleets deployed and capture better economics from existing assets.
This helps explain why PTEN and ProPetro made larger advances this quarter, while ACDC's operating improvement did not translate into a higher ranking. The difference is increasingly about the quality and commercial value of deployed capacity, rather than activity alone.
Relative Valuation
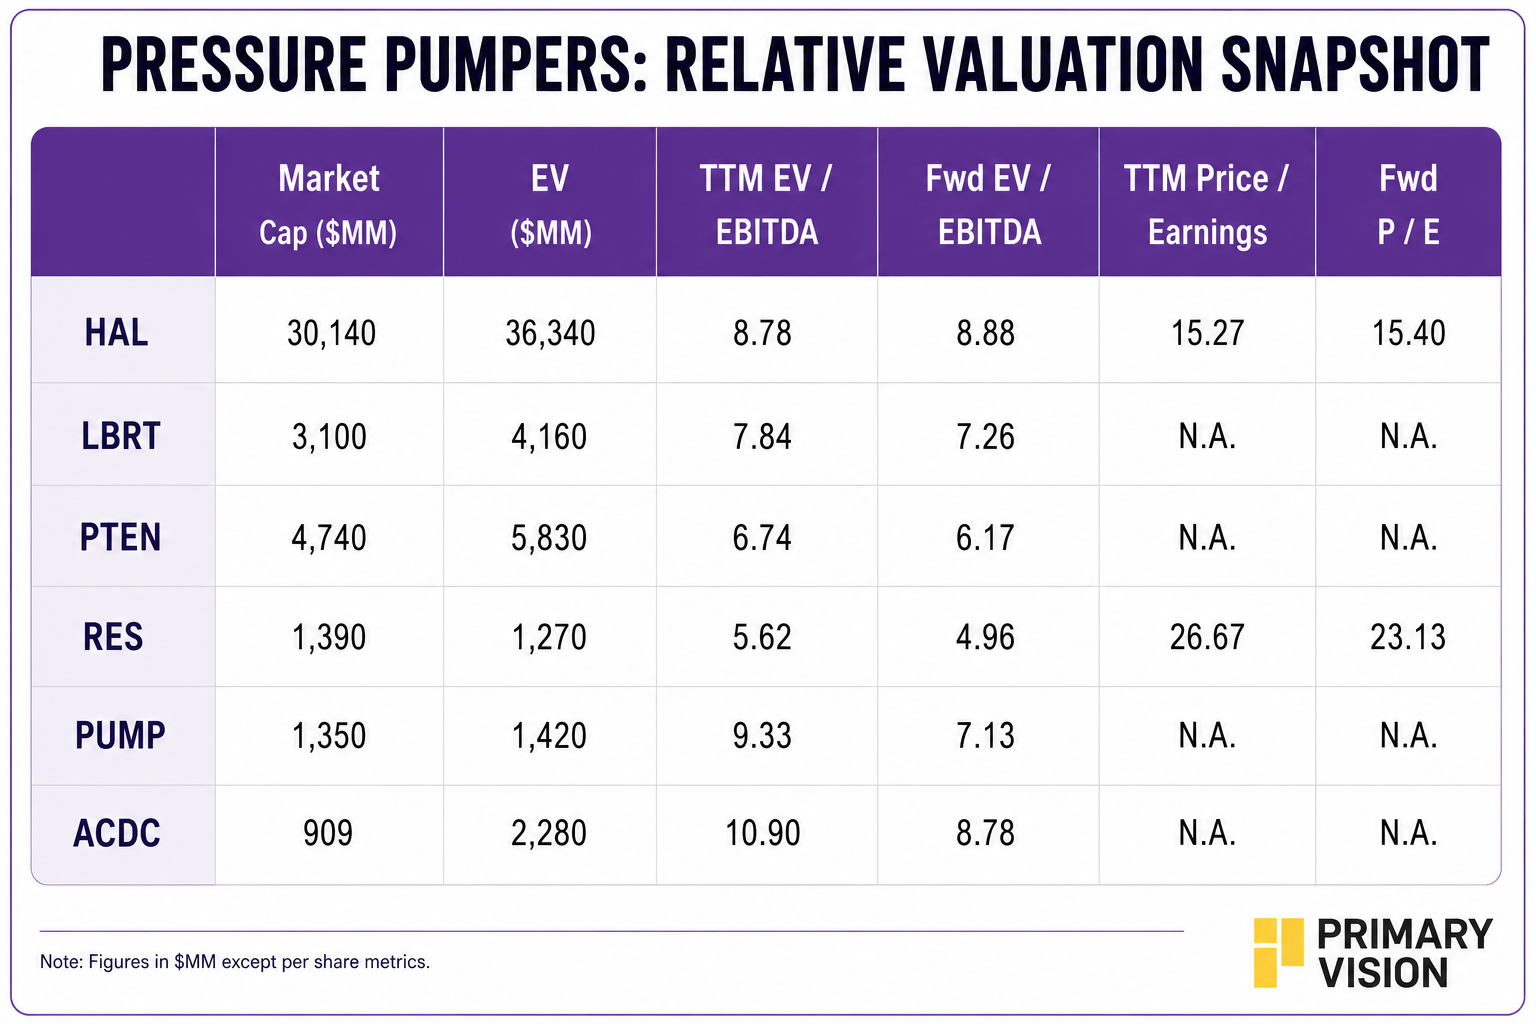
Liberty and Patterson-UTI remain two of the more attractively valued names, consistent with their ranking positions. Halliburton screens relatively unfavorably on its stable margin. PUMP and ProFrac reflect a trade-off between growing exposure to power-related opportunities and capacity constraints.
Takeaway
The Q2 ranking shows a pressure-pumping market in which tightening capacity is increasingly influencing the sector's economics. Liberty retains the top position, and Halliburton strengthens its second-place position, while PTEN and ProPetro make the largest advances.
The more important shift is below the leaders. Companies with improving utilization, pricing, and differentiated fleet or power exposure are gaining relative ground, while companies improving more slowly are losing ground. The ranking is therefore beginning to reflect not simply who is executing well, but also who is best positioned to monetize the tightening of capacity.
Tags:
Permission denied
Upgrade to Pro Today and get…
• This article — plus dozens more each month, all within our full Research Module
• Frac Hits — our National-Level Frac Spread Count and Frac Job Count, updated weekly
• Frac Operator Monitor — detailed FSC & FJC by operator
• And so much more, designed to help you track, forecast, and outperform