Outlook Explained
RPC’s (RES) completion activity improved during 9M 2026, with stronger customer demand across several service lines, particularly coiled tubing, nitrogen, and snubbing. Management cited improving drilling and completion activity and a more favorable operating environment. However, competitive pricing and rising labor, trucking, and fuel costs continue to pressure margins. RPC’s diversified completion services portfolio and strong balance sheet provide flexibility to respond to sustained customer demand while maintaining capital discipline.
The most significant development was the $74.5 million non-cash impairment of Pintail, RPC’s wireline business. Management cited persistent pricing weakness, lower activity, and cost pressure. The impairment signals weaker expected economics for the wireline operation.
Segment Performance
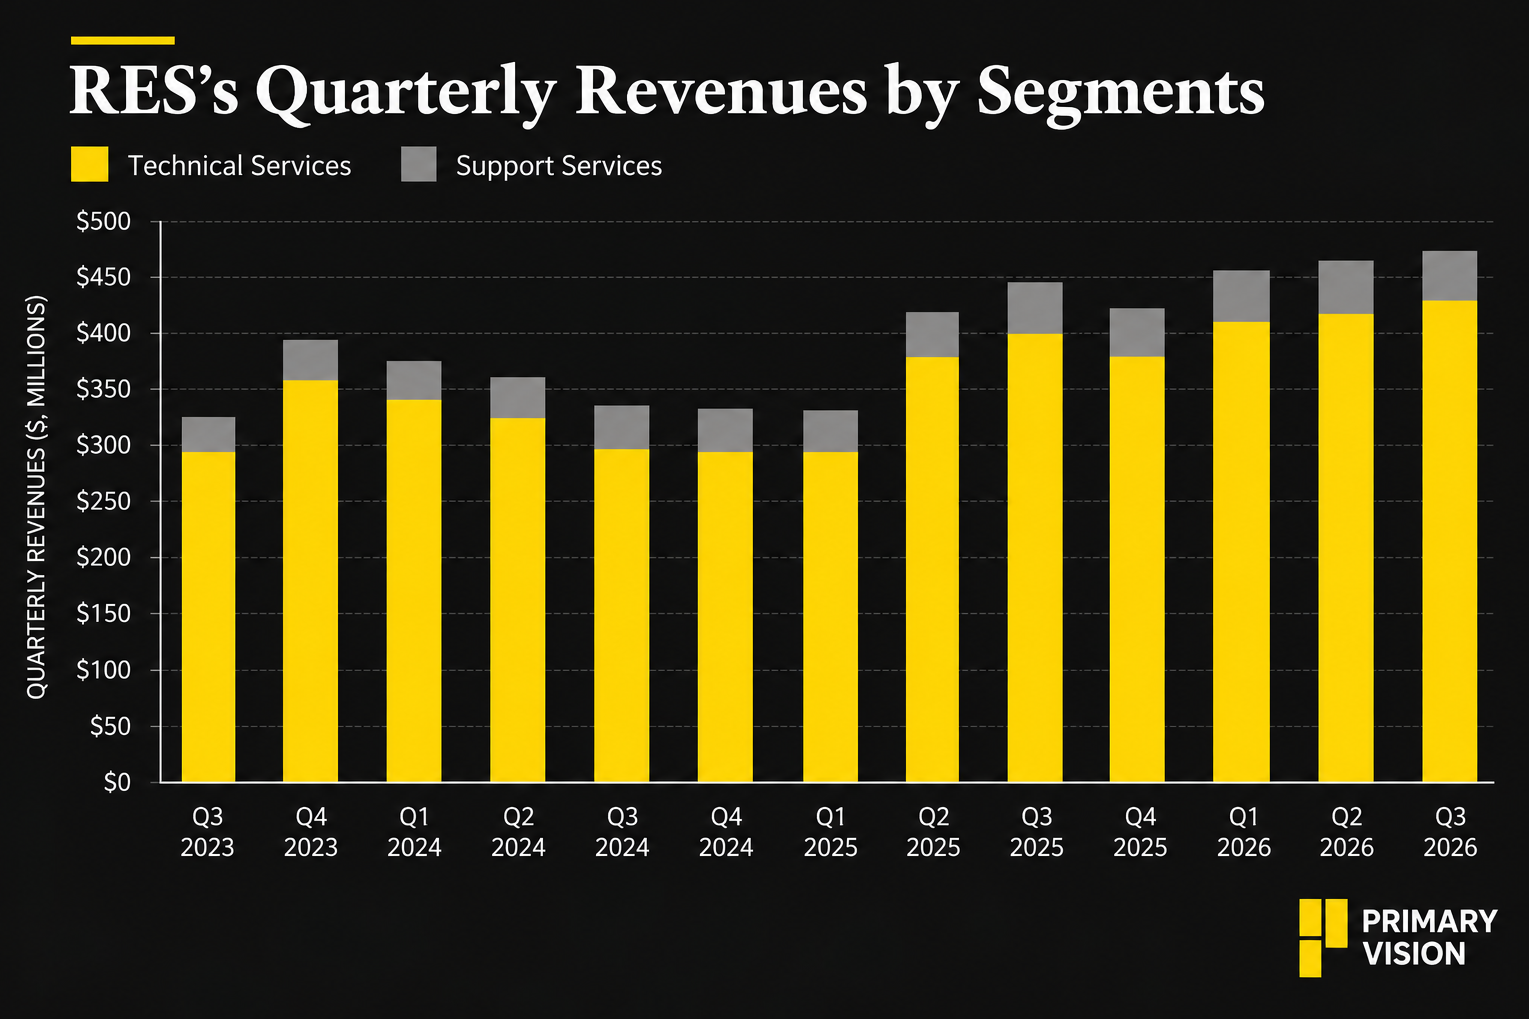
Technical Services revenue increased 1% sequentially, while operating income rose 5% in Q3 2026. Coiled Tubing, Nitrogen, and Snubbing each grew at double-digit rates, partly offset by lower Pintail Wireline revenue. The segment’s results show improving activity in several service lines, but the wireline business remains a material drag.
Support Services revenue increased 3%, while operating income rose 56%. Patterson Rental Tools led the segment. The improvement reflects stronger rental activity and the benefit of fixed-cost operating leverage.
Cash Flows & Capital Allocation
Cash generation remained weak year-to-date. Operating cash flow declined 17%, while free cash flow fell 77%. A rise in working capital represented cash through higher receivables, collection timing, and strategic inventory purchases. RPC repaid $20 million of notes payable, reducing notes payable to $30 million.
Thanks for reading the RES Take Three, designed to give you three critical takeaways from RPC's earnings report. Soon, we will present a second update on RES earnings, highlighting its current strategy, news, and notes from our deeper dive.