FTI’s Strategy Explained
We have already discussed TechnipFMC's (FTI) Q2 2026 financial performance in our recent article. This article will dive deeper into the industry and its current outlook. TechnipFMC expects stronger Subsea order activity in the second half, supporting its $10 billion inbound order target for 2026. Management also expects Surface Technologies margins to improve despite lower revenue through disciplined customer and project selection. The company strengthened its position in the Middle East through ADNOC's in-country value program.
TechnipFMC raised its full-year EBITDA guidance on improving business momentum. Management also expects Subsea order growth to accelerate further in 2027 and continue through the end of the decade. However, some risks remain. Subsea order intake could fall short if second-half bookings or expected direct awards are delayed, putting pressure on the company's $10 billion inbound order target for 2026.
Shareholder Returns
TechnipFMC returned $725 million to shareholders during 1H 2026, equal to 95% of free cash flow. Management continues to prioritize share repurchases as a key use of excess cash. The company also reaffirmed confidence in stronger EBITDA performance in 2026 and continued Subsea growth in 2027.
Outlook And Key Drivers
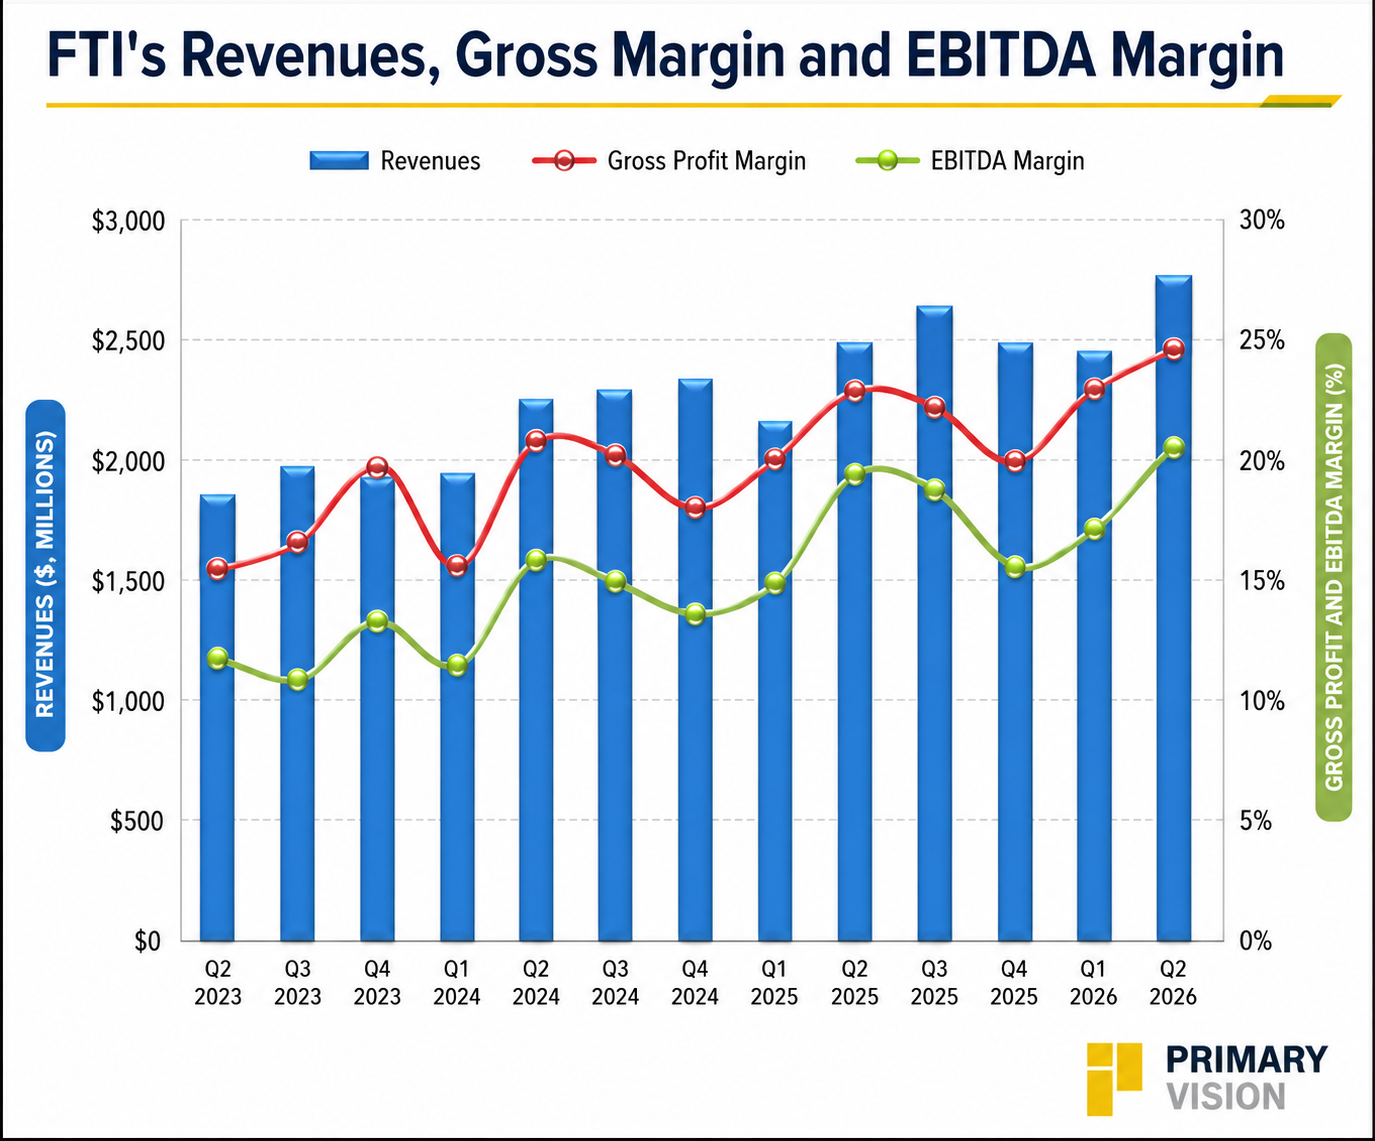
FTI’s management expects Subsea revenue and margins to remain broadly flat in Q3, while Surface Technologies revenue is projected to increase by approximately 5–9% sequentially. The company also expects Surface Technologies' EBITDA margin to reach about 17.5%. For FY2026,
TechnipFMC raised its EBITDA guidance by roughly 2% to approximately $2.19 billion and expects free cash flow to reach the high end of guidance at about $1.45 billion. Management also expects Subsea revenue and margins to finish near the top end of the previous guidance range.
Relative Valuation
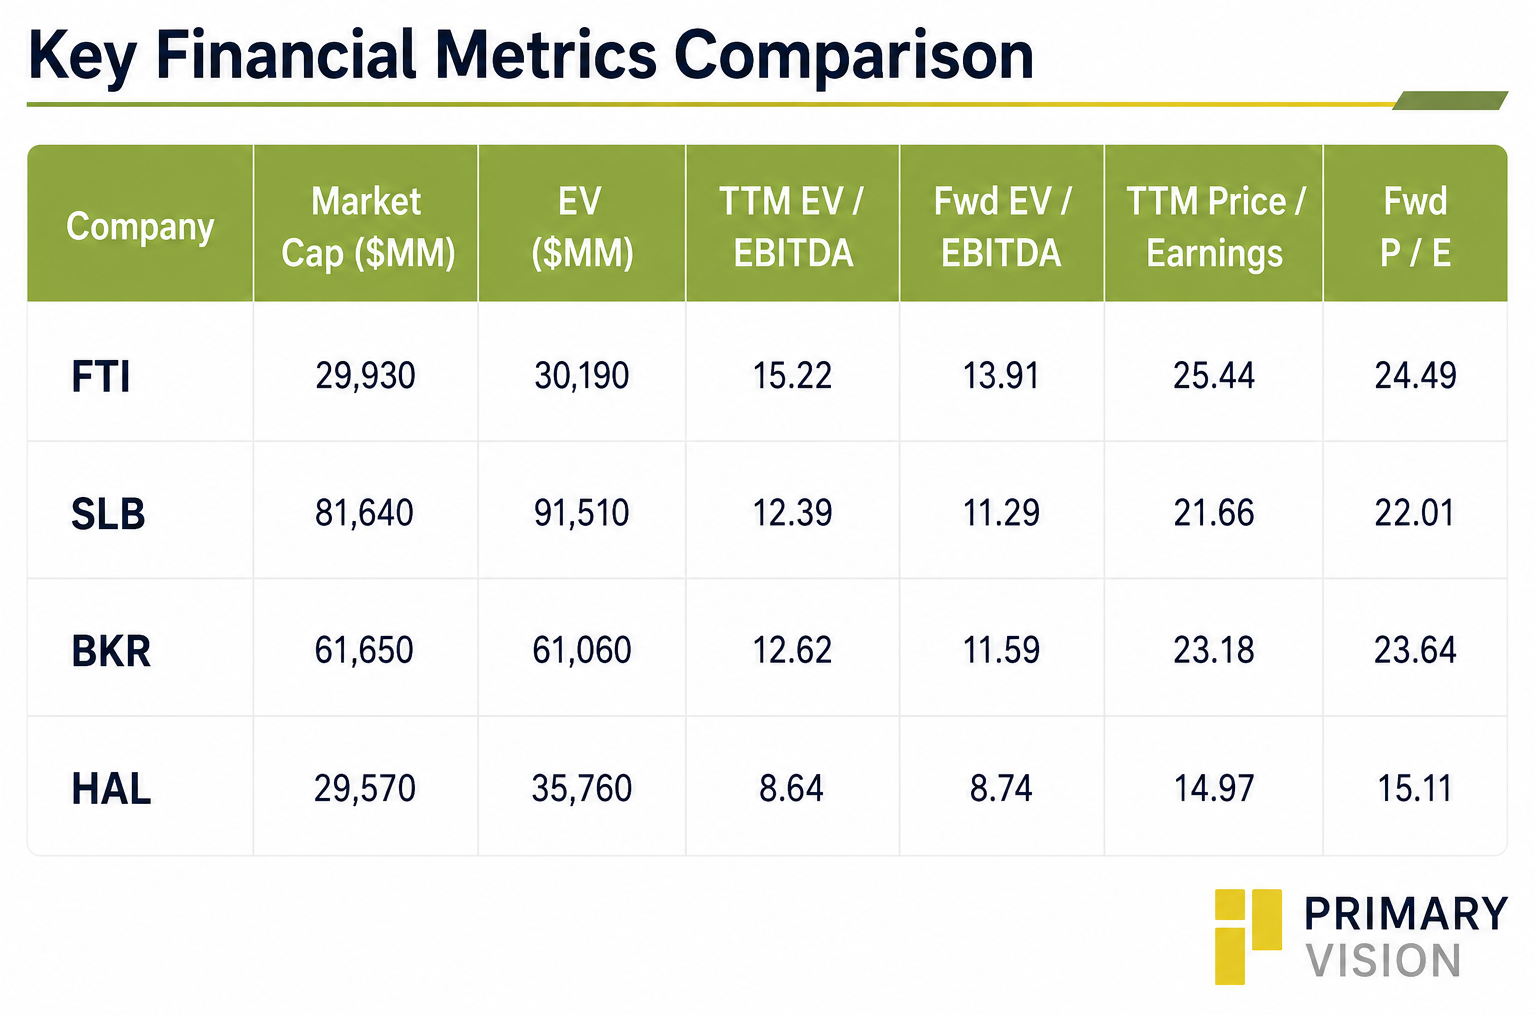
FTI is currently trading at an EV/adjusted EBITDA multiple of 15.2x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is 13.9x. The current multiple is higher than its five-year average EV/EBITDA multiple of 11x.
FTI's forward EV/EBITDA multiple contraction versus the adjusted current EV/EBITDA is steeper than peers' because the company's EBITDA is expected to increase more sharply in the next four quarters. This typically results in a higher EV/EBITDA multiple than peers. The stock's EV/EBITDA multiple is higher than its peers' (SLB, BKR, and HAL) average of 11.2x. So, the stock is reasonably valued compared to its peers.
Final Commentary
TechnipFMC expects stronger Subsea order activity in 2 2026, supporting its $10 billion inbound order target for 2026. Management also expects Subsea growth to accelerate further in 2027, driven by iEPCI, Subsea 2.0, and direct awards. However, delays in second-half project awards remain the key risk to its 2026 order outlook.
Surface Technologies continues to improve margins through disciplined project selection and execution. TechnipFMC also returned 95% of first-half free cash flow to shareholders through share repurchases and other distributions. The stock is reasonably valued compared to its peers.