Outlook Improves Despite Geopolitical Headwinds
Middle East disruptions continue to delay recovery, but Weatherford expects a meaningful earnings ramp in Q4 and sees significant growth opportunities in 2027. The completed NCS Multistage acquisition strengthens its completions portfolio, while the planned Delaware re-domestication (moving Weatherford’s legal corporate home from Ireland to Delaware) could generate $20–30 million in annual savings from 2027. Redeeming $236 million in senior notes should save ~$20 million annually in interest, further supporting free cash flow and financial flexibility.
Weatherford secured international contracts spanning offshore completions in Norway, artificial lift in Venezuela, managed pressure drilling in Indonesia and Argentina, and intervention services in Australia. These awards should support future revenue visibility and equipment and service utilization, although contract values and expected earnings contributions were not disclosed. The projects reinforce Weatherford’s international footprint and technology-led growth strategy.
Segment Results Analyzed
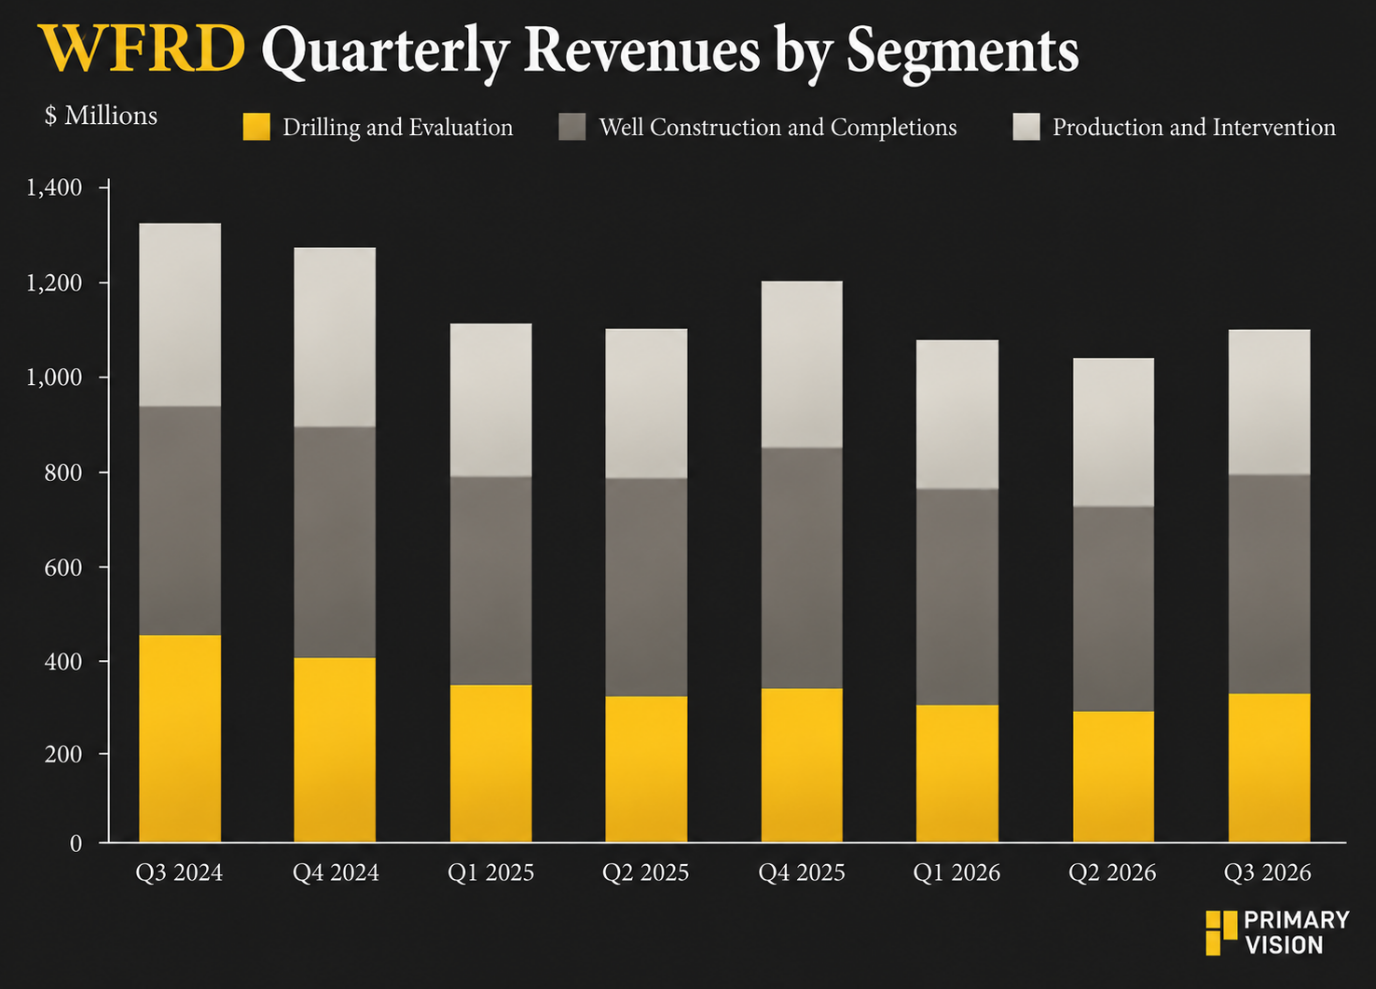
Drilling & Evaluation revenue increased 14% sequentially, while adjusted EBITDA rose 55%, expanding margins to 27.2%. Higher drilling services and managed pressure drilling activity in Latin America and the Middle East drove the improvement.
Well Construction & Completions revenue increased 4%, but adjusted EBITDA declined 7% as margins contracted to 22.2%. Stronger North American completions activity was offset by weaker operating flow-through.
Production & Intervention revenue slipped 1%, but adjusted EBITDA increased 4%. Improved artificial lift, subsea intervention and international operating performance supported margin expansion.
Cash Flows & Shareholder Returns
Operating cash flow was up by 23%, while free cash flow rose 55% sequentially year over year in 1H 2026. Weatherford returned $47 million to shareholders during Q3. Following Q3-end, it announced the redemption of its remaining $236 million of 8.625% senior notes, which is expected to reduce annualized interest expense by ~$20 million.
Thanks for reading the WFRD Take Three, designed to give you three critical takeaways from Weatherford's earnings report. Soon, we will present a second update highlighting WFRD's strategy, news, and insights from our deeper dive.