Completions & Frac Update
In our recent article, we have already discussed RPC's (RES) Q2 2026 financial performance. Here is an outline of its outlook. RPC’s management prefers to generate strong full-cycle returns rather than pursue uneconomic growth. The company does not plan to reactivate additional frac fleets under current market conditions. Management expects improving gas takeaway capacity and potentially stronger 2027 E&P budgets to support future activity.
Commodity price volatility continues to make operators cautious about increasing spending. The company remains focused on cash flow generation while staying prepared to respond to changing market conditions.
Frac Spread Strategy
RES has no plans to add or reactivate frac fleets under current market conditions. The company continues to selectively upgrade older equipment to newer natural gas-powered technologies while maintaining disciplined capital allocation. Management remains focused on investing only where it can generate attractive long-term returns.
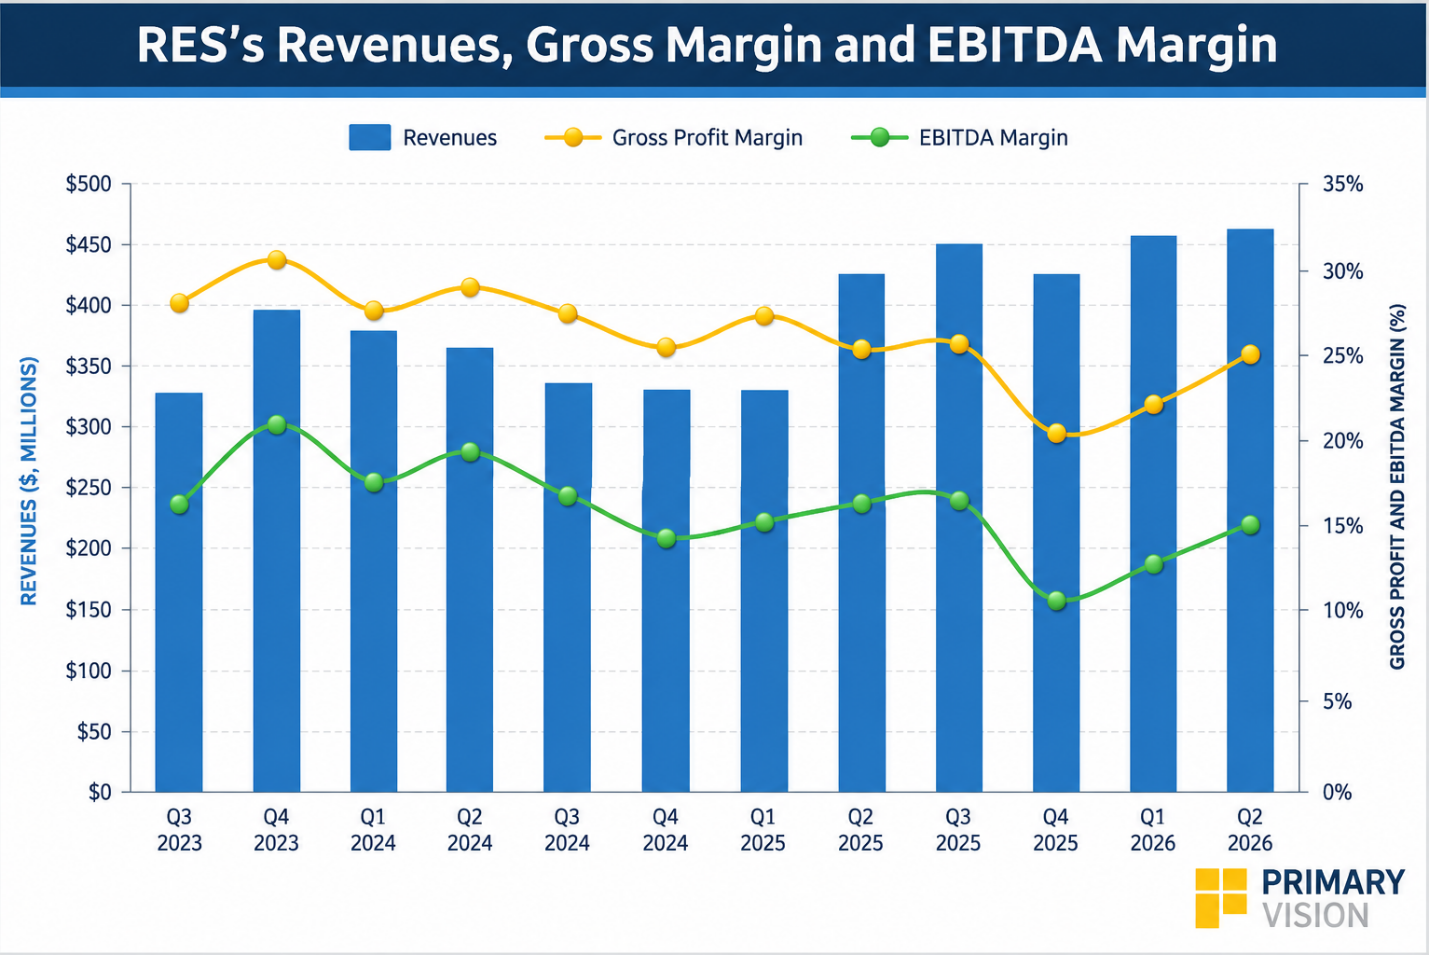
Other Completion Business Outlook
RES continues to expand its Thru Tubing product portfolio with new downhole technologies and Metal Max power section enhancements. It believes these technologies improve drilling efficiency, reduce non-productive time, and expand the addressable market. The business also achieved strong performance on complex, long-lateral Permian wells and continued customer adoption of its Unplugged technology.
In Q2, Cudd Pressure Control delivered sequential growth, led by coiled tubing and snubbing services. Management also continues to diversify the business through opportunities such as cavern gas storage inspection services.
Relative Valuation
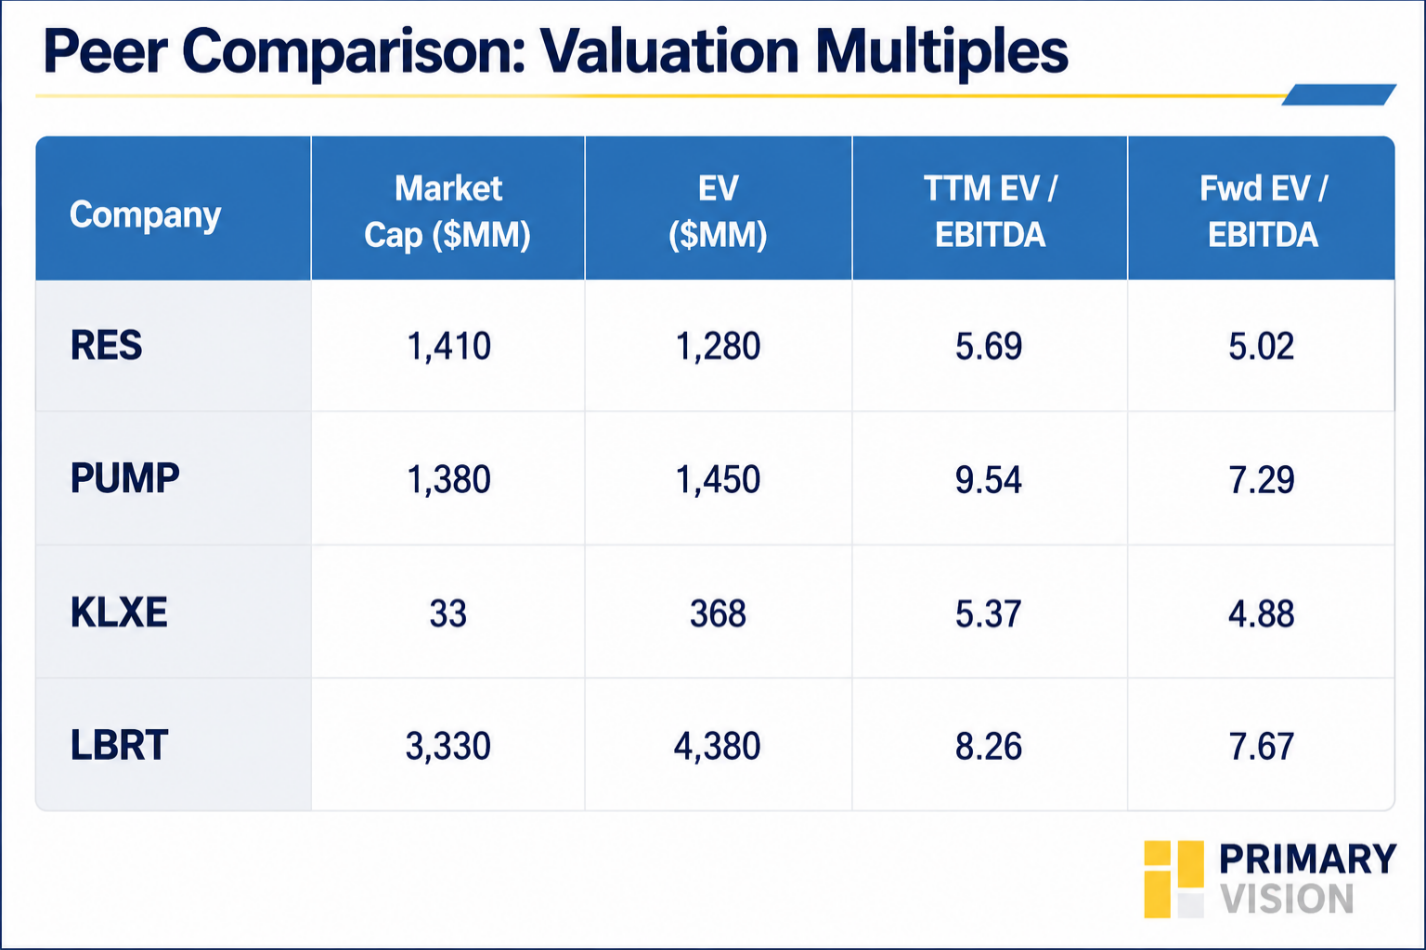
RES is currently trading at an EV/EBITDA multiple of 5.7x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is 5.0x. The current multiple is significantly lower than its five-year average EV/EBITDA multiple of 10.6x.
RES's forward EV/EBITDA multiple is expected to contract nearly as steeply as its peers. This implies that the company's EBITDA is expected to increase almost as sharply as its peers in the next four quarters. This typically results in a similar EV/EBITDA multiple. The stock's EV/EBITDA multiple is lower than its peers' (PUMP, KLXE, and LBRT) average of 7.7x. So, the stock appears undervalued compared to its peers.
Final Commentary
RPC prioritizes full-cycle returns over adding frac capacity in the current market. Improving gas fundamentals could support stronger activity in 2027, although commodity price volatility is keeping operators cautious. Fleet investments are directed toward upgrading to more efficient natural gas-powered equipment rather than expanding horsepower.
Cudd Energy is strengthening its completions portfolio with advanced Thru Tubing technologies designed for increasingly complex wells. Growth in pressure control services and new industrial applications is broadening the company's revenue opportunities. The stock appears undervalued compared to its peers.